4-hour battery storage is cheaper to install than gas turbines all across globe
Global Energy Shift: 4-Hour Battery Storage Outperforms Gas Turbines on Cost
By Kelly Pickerel | October 8, 2026
According to the most recent global report on the Levelized Cost of Electricity (LCOE) from Wood Mackenzie, a pivotal economic transition is underway. In every one of the 43 markets analyzed where both technologies were present, 4-hour battery storage has officially become more cost-effective to install than open-cycle gas turbines.
The Economic Catalyst
The shift is being driven by a combination of maturing technology and volatile market forces. While gas-peaking costs are climbing due to fuel instability and a shortage of turbines, the massive scaling of battery production is aggressively driving prices downward.
"This economic shift is decisive and widening," notes Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie.
Cost Driver Dynamics
Global Benchmarks & Solar Dominance
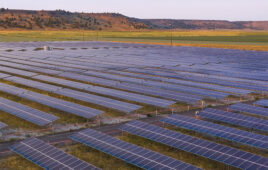
The report highlights that single-axis tracker solar is now the most affordable new-build option in 43 out of 48 modeled markets. In only five markets does onshore wind hold the lead.
| Region/Market | Key LCOE Metric | Forecast/Detail |
|---|---|---|
| Saudi Arabia & UAE | \text{LCOE} < \20/\text{MWh}$ | Expected by 2033 |
| Middle East & Africa | \text{Solar} = \37/\text{MWh}$ | Storage to drop 33% to \80/\text{MWh}$ by 2035 |
| China | below Asia Pacific average |
Regional Deep Dives
🌎 Latin America
In 2026, solar PV utilizing single-axis tracking remains the region's cheapest generation method.
- Cost Projections: Average costs are anticipated to decrease by by the year 2060.
- Regional Leaders: Brazil, Mexico, and Chile benefit from high-capacity factors and premier solar resources.
- Wind Trends: Onshore wind is seeing a steep decline:
- Current 2030: \73/\text{MWh} \rightarrow $58/\text{MWh}\approx 21%$ drop).
- Drivers: Larger turbines and the expansion of Chinese OEMs.
- Storage & Offshore:
- Storage LCOE forecast to fall by 2060.
- Offshore wind parity with combined-cycle gas (before firming) not expected until the early 2040s.
🌏 Asia Pacific
While utility-scale solar is the most competitive source here, the price variance between markets is extreme.
{
  "APAC_Solar_Disparity": {
    "2026_Gap": "Highest cost market is >200% more expensive than lowest",
    "2030_Forecast": "Gap expected to widen to 250%"
  },
  "Onshore_Wind": {
    "Price_Range": "6x difference between cheapest and costliest markets",
    "Trend": "Chinese OEMs narrowing the gap with coal in SE Asia"
  }
}
China continues to set the global pace. Its storage LCOE is more than lower than the broader Asia Pacific average of \134/\text{MWh}$92/\text{MWh}$ by 2036, countries like Australia, Japan, and the Philippines will still pay a premium due to domestic policies and import duties.
🇪🇺 Europe
Solar PV remains the most affordable technology. Fixed-tilt LCOE is projected to drop by 2060, despite a price drop 14% capex increase in 2026 caused by higher module costs.
- Onshore Wind: Capex is falling by annually this decade, with LCOE hitting \60/\text{MWh}$ by 2060.
- Battery Storage: Turnkey capex rose (the first increase in three years) as lithium prices rebounded from 2025 lows.
- Short-term: drop by 2031.
- Long-term: Pace slows in 2029 as lithium prices roughly double due to demand outstripping mine capacity.
- Fossil Fuels: Europe has the highest costs globally; by 2030, levelized carbon costs are expected to exceed actual fuel costs.
🇺🇸 North America
The landscape in North America is currently volatile due to regulatory pressures.

Key Pressures:
- Tariffs & Duties: Anti-dumping and countervailing actions are inflating costs.
- Import Restrictions: New Sec. 232 restrictions are impacting the market.
- Sector Impact: Distributed generation is the most exposed.
While utility-scale solar has a buffer thanks to 168 GW of safe-harboured capacity, module prices are still predicted to climb annually through 2030. Commercial and residential sectors face steeper hikes: in 2027 and in 2028.